Buying a Plex: Rental Income, Expenses and Financing
Estimate cautious rental income, add taxes, insurance and a repair reserve, then test the financing on that basis.
Published 2026-07-21
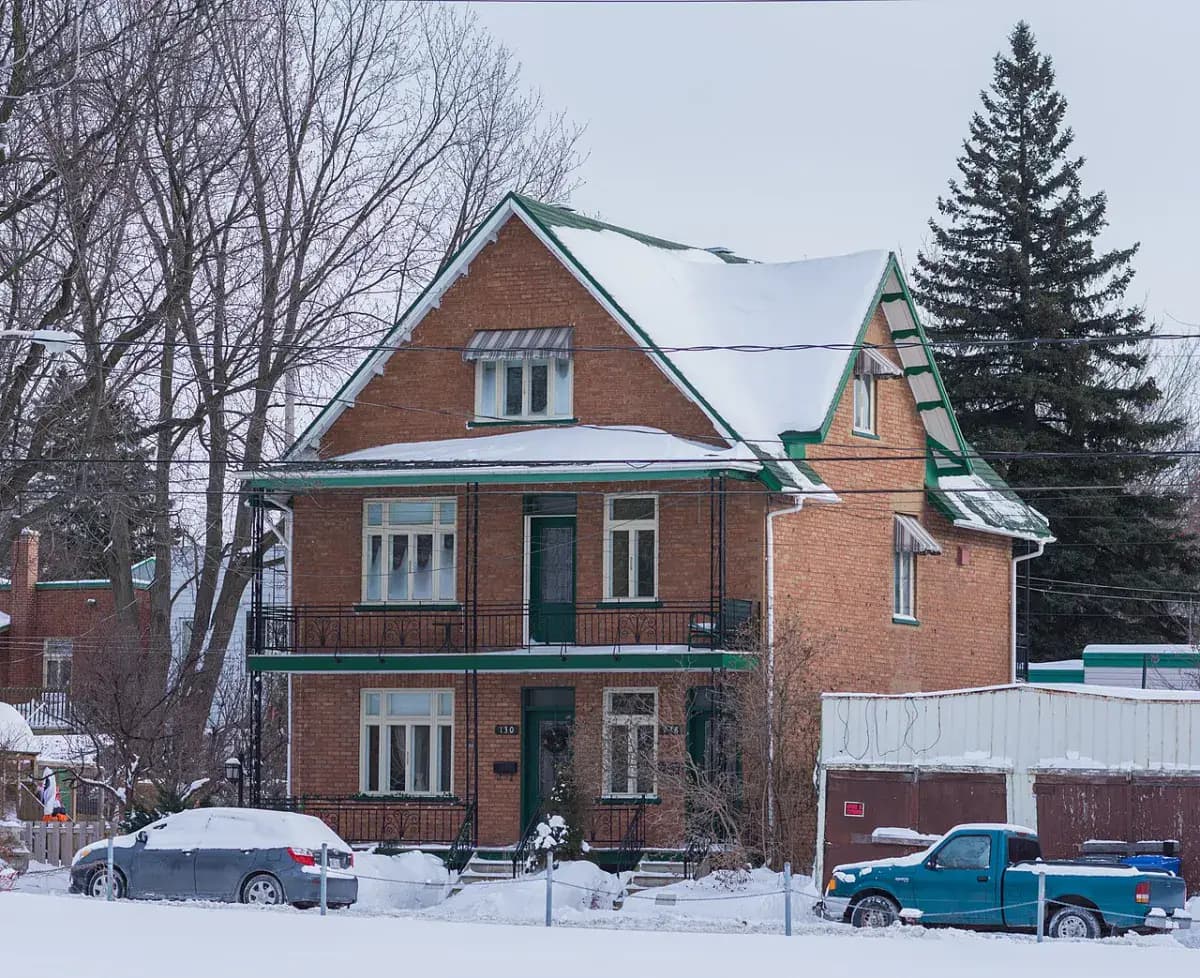
A plex always comes with a story: advertised rents, promising cash flow, a listing sheet built to make you dream. The purchase gets decided on a different basis. Real income comes from the signed leases, trimmed by a vacancy allowance; complete expenses include taxes, rental-building insurance, maintenance, snow removal and a repair reserve the listing never mentions. Financing follows its own rules: the required down payment depends on occupancy, and the lender counts only a fraction of the rents toward qualification. Between the seller's story and the buyer's arithmetic, the gap often amounts to tens of thousands of dollars on the maximum reasonable price. This article walks through rebuilding cautious income figures, drawing up the complete expense list, testing the financing and setting a price that still holds when one unit sits empty for three months. The building that survives that math is the one worth owning.
Rebuild the income from the leases
A plex's income is proven, not announced. Request each unit's signed lease and compare them with the sales sheet: gaps of several thousand dollars a year are common, between hoped-for and actual rents, vacant units counted as rented, or imminent renewals with contested increases. Note each lease's end date and exact rent, then subtract a realistic vacancy allowance — one month per unit every two years, say. Also verify who pays heat and electricity: a building with utilities included carries expenses the gross income hides. The resulting figure, lease income minus vacancy, becomes the sole basis for every calculation that follows, from cash flow to the offer price. Any analysis built on the advertised number inherits its optimism.
Price the expenses the sheet leaves out
Sales sheets display the taxes and often stop there. The complete picture includes rental-building insurance, noticeably costlier than a residential policy; routine maintenance estimated at about one percent of value per year; snow removal and lawn care; and a repair reserve for the roof, balconies or furnace that will eventually give out. Add a management provision even if you self-manage: your time collecting rent, showing units and answering emergency calls has value, and the day you delegate, the expense becomes real. Line these figures up beneath the cautious income: many buildings with advertised positive cash flow turn red at this step, before financing even enters the picture. The column that survives is the one worth financing.
Understand the lender's rules
Financing a plex follows rules of its own that pivot on one central factor: occupancy. A building where you will live in one unit finances with a smaller down payment than a fully rented one, but the lender will count only a fraction of the rents toward your qualification, using its own calculation method. Ask precisely: what percentage of rental income enters the calculation, and how is the owner-occupied unit treated? The answer determines the amount actually borrowable — often far from what the gross income suggested. Obtain a preapproval based on the target building rather than your salary alone, and keep the purchase offer conditional on financing as well as lease verification. The lender's arithmetic, not the seller's, sets the ceiling.
Test the worst quarter before signing
A plex profitable on paper must survive its worst quarter: one unit empty for three months, a tax increase, a water heater and a balcony in the same year. Simulate that scenario with your cautious numbers: if the mortgage payment then requires your credit card, the price is too high or the reserve too thin. Set the maximum price that keeps the bad scenario absorbable, and fund the repair reserve before taking possession rather than after the first emergency. Also anticipate rent variation across renewals and the work that conditions increases. The building that passes this test at your price is an asset; the one that passes only at the seller's price is a bet — and the test costs nothing but an evening.
Quebec scenario: compare before confirming
A couple in Trois-Rivières visits a triplex with two rented units. The seller advertises $28,800 in annual income, but the leases show $26,400 and one unit will be vacant in July. The couple redoes the math using the signed leases, adds taxes, insurance, maintenance and a repair reserve of 1% of the property value, then subtracts one month of vacancy per unit. The monthly cash flow moves from an apparent $310 surplus to a $140 shortfall. Because one of them will live in the building, the lender counts only part of the rent toward qualification. They lower their maximum price accordingly and keep their offer conditional on verifying the leases and the actual expenses. Before lifting the financing condition, they also ask the seller for the utility bills and the insurance renewal, since heated units and an older roof change the premium. The building only makes sense at a price where a vacant month never forces them to borrow.
Checklist
- Obtain the signed leases and compare them with advertised rents
- Subtract a vacancy allowance from the income
- Price taxes, insurance, maintenance and a repair reserve
- Verify the down payment required by occupancy
- Ask what fraction of rents counts toward qualification
- Test the cash flow with one unit empty for three months
- Set the maximum price from the math, not the listing
- Keep the offer conditional on lease verification
- Fund the reserve before taking possession
Frequently asked questions
Can I use the rents advertised by the seller in my math?
No. Work from the signed leases, not the listing sheet. Verify the amounts, the lease end dates and any vacant units, then subtract a vacancy allowance. A gap between advertised rents and actual leases is common and changes the cash flow directly.
Does the lender count all the rent toward my qualification?
Rarely in full. Depending on whether you will live in the building, the lender counts only a fraction of rental income, using its own method. Ask for the percentage applied before setting your maximum price, because it determines the amount you can actually borrow.
What reserve should I plan for a plex?
Plan at least 1% of the building's value per year for maintenance and repairs, plus a cushion covering a few months without rent. A building that is profitable on paper but has no reserve becomes fragile at the first vacant unit or the first roof.